CONTRIBUTED CONTENT: Finding hidden assets after a loved one dies
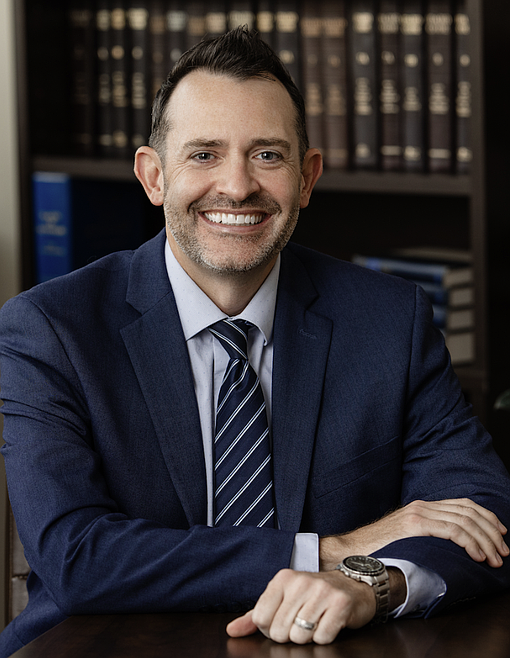
Robert J. Green, Esq.
When a parent or spouse passes away, families often discover that the paperwork doesn't tell the whole story. An old 401(k) from a job decades ago, a life insurance policy no one knew about, a forgotten bank account: these assets are surprisingly common, and without some detective work, they can stay lost for good.
If you're serving as a personal representative or trustee in Idaho, finding everything your loved one owned is part of the job. Here's where to start.
Follow the Mail and the Paper Trail
The single best clue is often the mailbox. Account statements, dividend checks, insurance premium notices, and tax forms tend to arrive on a regular schedule. A personal representative can arrange with the post office to forward the decedent's mail, which is worth doing for at least a year so annual statements have time to show up.
Next, go through files, desk drawers, and filing cabinets. Look for checkbooks, old statements, policy documents, stock certificates, and savings bonds. Even a canceled check made out to an insurance company can point to a policy about which you otherwise might have no info.
Check the Tax Returns
Recent tax returns are a roadmap. Interest and dividend income points to bank and brokerage accounts. Retirement distributions reveal IRAs and pensions. If you can't find copies, the personal representative can request tax transcripts from the IRS, which list the income forms that were reported under the decedent's Social Security number.
Search Unclaimed Property Databases
When an account sits inactive long enough, the bank or company eventually turns the money over to the state. Idaho's unclaimed property program, run by the State Treasurer's office, holds millions of dollars in forgotten bank balances, uncashed checks, utility deposits, and insurance proceeds.
Search Idaho's database first, then search every state where your loved one lived or worked. The multi-state site MissingMoney.com covers most states at once. Searching is free, and you should never need to pay a "finder" service to do it for you.
Track Down Life Insurance
People often buy policies and never mention them, or get coverage through an employer that the family forgets about. The National Association of Insurance Commissioners offers a free Life Insurance Policy Locator (naic.org) that asks participating insurers to check their records for policies on the decedent. If a policy turns up, the insurer contacts the beneficiary directly.
Also check with former employers, unions, credit card companies, and professional associations, which sometimes provide small accidental death or group life benefits.
Look for Old Retirement Accounts
Workers who changed jobs over a long career may have left behind 401(k)s or pensions. Contact former employers directly, and check the U.S. Department of Labor's Retirement Savings Lost and Found database (lostandfound.dol.gov), which helps people locate employer retirement plans. For pensions from companies that have closed or merged, the Pension Benefit Guaranty Corporation (pbgc.gov) may be holding benefits.
Don't Forget Savings Bonds
Paper savings bonds tucked in a drawer, or electronic bonds held in a TreasuryDirect account, are easy to overlook. The U.S. Treasury's Treasury Hunt tool (www.treasurydirect.gov/savings-bonds/treasury-hunt/) can search for matured bonds that were never cashed.
Pull a Credit Report
A credit report won't show bank balances, but it lists credit accounts, mortgages, and loans. That helps you identify both debts that need to be handled and financial institutions where your loved one may also have had deposit accounts. If the decedent had a loan from a bank, they may have also held accounts there.
Safe Deposit Boxes and Digital Clues
If you find a key or a bank lists a box rental fee, there may be a safe deposit box. Banks have their own procedures for access after death, often requiring court appointment papers or other documentation if you are not already a person authorized to access the box.
Don't overlook email inboxes and phone apps either. Statements and account alerts increasingly arrive electronically, and an email search for "statement," "account," or "policy" can turn up a lot.
A Gift You Can Give Your Family Now
The easiest way to spare your family this search is to create a simple asset inventory: a list of your accounts, policies, and where important documents are kept. Store it with your estate planning documents and update it every year or two. It doesn't necessarily need to include passwords, just enough information to point your loved ones in the right direction.
My law firm is currently offering free telephonic, electronic, or in-person consultations concerning probating estates or creating estate planning documents.
• • •
Robert J. Green is an Elder Law, Trust, and Estate Planning Attorney and the owner of Kootenai Law Group, PLLC in Coeur d’Alene. If you have questions about estate planning, probates, wills, trusts, or powers of attorney, contact Kootenai Law at 208-765-6555, [email protected], or visit www.KootenaiLaw.com.
This has been presented as general information and not as legal advice. Do not engage in legal decision-making without the advice of a competent attorney after discussion of your specific circumstances.